Innovate UK is part of UK Research and Innovation
This report was commissioned from the innovation foundation Nesta by Immerse UK with funding from Innovate UK. Immerse UK is a special interest group for immersive technologies set up in 2016 by Innovate UK's Knowledge Transfer Network. It brings together 1,700 leading businesses, researchers, activists, thinkers and investors, to position the UK as a global leader in immersive technology.
Innovate UK is part of UK Research and Innovation, a non-departmental public body funded by a grant-in-aid from the UK government. We drive productivity and economic growth by supporting businesses to develop and realise the potential of new ideas, including those from the UK’s world-class research base.
Immerse UK is managed by the Knowledge Transfer Network and supported by Innovate UK. It brings together researchers, funders and investors to support the UK in becoming a global leader in immersive technologies.
The Knowledge Transfer Network is a network partner of Innovate UK and helps businesses to get the best out of creativity, ideas and the latest discoveries and strengthen the UK economy.
Innovate UK
Knowledge Transfer Network
Nesta is a global innovation foundation. It backs new ideas to tackle the big challenges of our time.
Glass reads the internet to produce structured market research and economic analysis.
MTM London is an independent research and strategy consultancy that specialises in media and technology sectors.
The report’s authors are:
Juan Mateos-Garcia,
Head of innovation mapping in Nesta Research Analysis and Policy
Konstantinos Stathoulopoulos,
Data science researcher, Nesta
Nick Thomas,
Associate director, MTM London
Foreword
The UK is home to world-leading tech sector and creative industries and in recent years we have seen them come together to develop innovative technology of tomorrow.
Digital tools, devices and platforms have given our world-class creative talent the opportunity to develop not just new content, but entirely new markets and industries.
One of the most exciting of these is immersive media and the ability to create new experiences for users with augmented or enhanced environments. From flight simulations, innovation displays in shops to new forms of surgical training techniques, the possibilities are endless.
As the immersive economy report confirms, Britain is a world-leader in this growing field but we cannot be complacent. This is why we are investing £33 million in immersive technology products, services and experiences as part of the Creative Industries Sector Deal.
This will support new uses of virtual reality in areas such as video games, interactive art shows and augmented reality experiences in tourism that will capture the world’s attention and double Britain’s share of the global creative immersive content market by 2025.
I welcome the UK immersive economy report as the first step in exploring this expanding sector as we seek to build on the UK’s position as a world leader in this technology.
Margot James MP
Minister for Digital and the Creative Industries
Help us to make UK a global leader
We established Immerse UK in 2016, and it was clear from our rapidly growing membership that the UK had an emerging ecosystem of immersive business practitioners, content producers, technologists and platform developers. It was also clear that these highly innovative businesses were applying their digital and creative skills not just to the creative industries, but also to other industrial sectors of our economy.
We saw amazing virtual reality applications, from the design and manufacture of cars to the development of new drugs using mixed reality spaces. Our conclusions, however, were anecdotal, built up from the range of successful network activities that we run with both industry and researchers.
One of Immerse UK’s priorities was to develop a better and more systematic understanding of the country’s strengths, specialisms and value in immersive technologies, with a view to encouraging greater levels of research and development in this exciting area.
In our first immersive economy report, we quantify and describe a fast-growing, confident and export-intensive industry that is already adding economic value to the UK. The findings provide the insights and intelligence needed to better support the complex needs of this emerging business community. The report reveals the richness of activity in immersive technology and its economic significance.
Importantly, the report defines the scale, nature and economic value of ‘immersive specialist’ businesses for the first time. This new and precise definition allows policymakers in the UK to chart the progress of this emerging but vitally important part of the digital and creative industries sector and its economic impact on other sectors. Consequently, we hope that this UK immersive economy report will be the first of many in the future.
Immerse UK is working with 1,700 leading businesses, researchers, activists, thinkers and investors to position the UK as a global leader in immersive technology. We can only do this by coming together and demonstrating the entire range of leading-edge products, services and applications being developed in the UK today.
A business I met recently told me: "This isn’t a new disruption or revolution as it is so often referred to, it is an evolution in the way we do business or engage with the world around us." I couldn’t agree more, and we look forward to continuing to evolve, taking our cue from market developments and member needs.
After reading this exciting report, I do hope that you too will join Immerse UK and help us to establish the UK as a global leader in immersive technology over the coming years.
Fiona Kilkelly
Immerse UK
Executive summary
Findings
We have used 2-dimensional media for centuries to access content and knowledge – pages in books and newspapers, screens in cinemas, televisions, computers and smartphones. Immersive technologies such as virtual reality, augmented reality and mixed reality take us further by placing us right inside incredible virtual environments. They enhance the world around us with useful, usable information. Immersive seems about to realise the dreams of science-fiction writers and futurists, transforming how we communicate, work and play.
There is much excitement about the growth prospects for the sector, and about the UK’s ability to reap the rewards of the immersive boom. Our historical strengths in arts, science and technology are coming together in new, globally leading ventures with strong backing from government.
This report, commissioned by Immerse UK with funding from Innovate UK, provides hard data about the size of the sector, its performance, its geography, the drivers of success and the barriers to growth. Information was gathered by Nesta, with help from Glass – a start-up with expertise in text mining from websites – and from strategy and research consultancy MTM London. It used methods that combined mining of data, a business survey and in-depth interviews.
1. Immersive is already an economic reality in the UK
We estimate there are 1,000 immersive-specialist companies in the UK employing around 4,500 people and generating £660 million in sales, potentially representing as much as 9% of the global market share. If UK specialists grow in line with market forecasts, they stand to generate over £1 billion in sales in 2018. We also estimate that half a million people work in companies with some participation in the immersive economy.
2. Immersive is a young, growing, confident and export-intensive sector
Half of immersive-specialist businesses in our data were incorporated since 2012, when the ‘immersive boom’ truly began. 6 out of 10 immersive specialists grew their turnover in the last 12 months, and 90% were confident about their future prospects. 70% of those we surveyed are exporting immersive-related products and services, with a particular focus on US markets.
3. Immersive companies are creating value in the creative industries and in many other sectors
Although 80% of the companies we surveyed operate in creative and digital markets, two-thirds mentioned other markets, ranging from education and training to architecture, advanced manufacturing and energy. Immersive technology produces a variety of benefits for its adopters, from increased competitiveness through innovative products to improvements in process and more visibility in the market.
4. Much of the immersive activity is concentrated in London, but there are hotspots of activity across the UK
38% of immersive companies are to be found in London, mirroring the picture across the digital and creative industries. Other locations across the UK have substantial numbers of immersive companies, including Brighton, Bristol, Newcastle, Liverpool, Manchester, Cambridge, Oxford and Edinburgh. Access to infrastructure and technological expertise are important drivers of success everywhere in the UK, while skills shortages are the biggest challenge for the sector.
5. Immersive is a young and emerging sector and suffers from fragmented technology ecosystems and issues with skills supply
More than 80% of the companies we surveyed identified issues with the technology ecosystem such as lack of device penetration and fragmented standards. More than two-thirds worried about access to skills and 60% of immersive specialists identified access to finance as a barrier. We found that immersive specialists tended to be stronger and more successful users of finance sources related to technology and start-ups, such as equity, accelerators and co-working spaces. In contrast, they relied less on loans, possibly due to their reliance on intangible assets and a lack of sectoral expertise among banks.
6. There has been a rapid expansion in the levels of public support for research and development in immersive technologies
We identified 253 immersive technology projects worth a total of £160 million in UK Research Councils, Innovate UK and EU Horizon 2020 open datasets. The funding devoted to immersive technology projects was 9 times higher in 2016-2017 than in 2009-2010. 3 in 10 immersive specialists benefited from tax incentives in the last 12 months, and 2 in 10 received some sort of national grant.
Introduction
Immersive technologies will deliver economic growth and transform the way we communicate, work and play
The sector’s growth prospects reflect its potential to reshape the way we communicate, work and play. Goldman Sachs forecasts that the market could be worth as much as $95 billion in 2025, while TechCrunch estimates the combined virtual reality/augmented reality market will reach $108 billion in 2021 . Citi are even more optimistic, forecasting a $569 billion market in 2025 . The stakes are clearly high.
What is the immersive economy?
We use the term ‘immersive economy’ to refer to the group of organisations (including businesses, university researchers and communities of developers and practitioners) developing or applying immersive technologies to create economic, social and cultural value. These technologies transcend traditional formats for interacting with digital information (screens), immersing users in digitally generated or enhanced realities, and include:
- virtual reality: ‘computer-generated simulation of a 3-dimensional image or environment that can be interacted with in a seemingly real or physical way by a person using special electronic equipment’ such as headsets and motion-control interfaces (Oxford Living Dictionary)
- augmented reality: ‘a type of interactive, reality-based display environment that takes the capabilities of computer-generated display, sound, text and effects to enhance the user’s real-world experience’ (Techopedia)
- mixed reality: ‘merging of real and virtual worlds to produce new environments and visualisations where physical and digital objects co-exist and interact in real time’ (Foundry)
- haptics communication: ‘recreates the sense of touch by applying forces, vibrations, or motions to the user’ (Wikipedia)
Immersive belongs to what economists call ‘general purpose technologies’ such as electricity or information and communication technologies . General purpose technologies can be broadly applied in many different areas, accelerating innovations across the economy. In our digitally mediated society, it is hard to think of a sector that immersive will not impact in some way.
The UK is well placed to reap benefits
The UK is in an excellent position to reap the rewards of this growth thanks to its world-leading digital technology, video games, visual effects and animation industries, and its strength in early immersive adopter sectors such as advanced manufacturing, advertising, architecture and engineering.
The technology and global market landscape are, however, fast-moving, and highly competitive. The UK is not the only country looking at this technology area. Supportive policy will be important for the sector’s future success. Key players such as Innovate UK, the Digital Catapult, the High Value Manufacturing Catapult, the Arts and Humanities Research Council and Engineering and Physical Sciences Research Council were early in recognising immersive’s strategic importance, not only as a high-growth, highly innovative STEAM-powered (science, technology, engineering, arts and mathematics) industry, but also as a potential driver of productivity and innovation elsewhere in the economy.
Better evidence can help identify new opportunities and remove barriers to growth, ultimately realising the potential of the sector. This report seeks to build strong evidence about the immersive economy using a method that combines mining of big data, a business survey and qualitative interviews.
How we gathered data
Emerging sectors such as immersive are hard to find in official data because they are too young to be included in the industrial codes that we use to organise our understanding of the economy . Official datasets also fail to capture the adoption of new technologies in existing sectors, yet this is very important to gauge their potential impact on productivity.
This is why we worked with Glass, a start-up that reads the websites of millions of UK businesses and analyses them using state-of-the-art text-mining methods to understand what they do . We were able to identify any company that mentioned immersive keywords in its website, regardless of whether it was a developer, a creator or a user.
We developed a list of keywords through an analysis of text used in Immerse UK members’ websites and at immersive technology meet-ups. Using this approach, we have been able to identify just under 2,000 UK organisations we consider part of the immersive economy.
Web data on its own is not enough to answer big policy questions about the size of the sector, its growth prospects, its drivers and its barriers. We carried out a survey with MTM London of the companies we identified online, resulting in 278 unique responses.
This survey has given us a wealth of information about the situation of the sector, as well as a ‘labelled’ dataset for a machine-learning exercise that has generated estimates of employment, turnover and level of engagement in the immersive economy for all companies in the data (including those that did not participate in the survey).
We tapped into web and open data sources to incorporate into our analysis two aspects of support for immersive companies – informal networks and research funding. We identified and mapped 43 communities of technology developers and enthusiasts interested in immersive technologies through Meetup.com, a popular web platform for organising events, and we have combined open data from UK Research Councils, Innovate UK and the EU (through its Horizon 2020 programme) to identify 253 immersive technology research and development projects.
We have also undertaken 10 immersive economy case studies of businesses based in different parts of the UK, and working in different industries and positions in the value chain, to allow the sector to tell its story in its own words. These case studies, spread across the report, bring to life and help to interpret our quantitative findings, and illustrate the range of sectors where immersive technologies are being applied.
The findings
The immersive economy is a young, growing, dynamic and confident sector
Immersive is already an economic reality
Our machine-learning analysis suggests there are just over 1,000 'immersive specialist' companies in the UK that generate more than 50% of their turnover from immersive products and services. We estimate that these companies employ around 4,500 people and generate a turnover of £660 million. These companies' areas of operation vary widely, from modelling and simulation companies offering virtual reality solutions to the defence industry, to games developers creating virtual worlds and stories, agencies developing immersive content for brands, and companies using virtual surgery to transform medical training. The variety of specialist companies we have identified reflects the breadth of opportunities for immersive technologies. This is the first time the richness of activity in the sector has been revealed in a data-driven way.
We also identified a group of 'immersive participant' companies that generate up to 50% of their turnover from immersive products and services. As with the specialists, participants come from all areas of the economy, from automotive design consultants to social enterprises and drone technology developers. These companies employ almost 500,000 people and generate £60 billion in turnover. This group includes some of the largest technology, energy and retail companies in the UK, and immersive activity will in most cases represent a small amount of their overall employment and turnover. However, we believe that the large area of the economy already touched by immersive technologies is a useful representation of the potential of the sector.
While experimental, our analysis generates more conservative estimates of the size of the sector than we would obtain if we simply scaled up the responses in the survey to the business population we identified online (this would suggest immersive specialists employ more than 10,000 people and generate a turnover of more than £800 million). Given the hype around the sector, it is important to provide credible, rigorous estimates of its size with the best data and most intelligent methods we have at hand.
Our analysis shows that there is economic substance behind all the excitement about immersive technology. Combined with existing revenue forecasts such as those produced by Goldman Sachs and TechCrunch, it suggests that UK immersive specialists could already be capturing as much as 9% of global market share in the sector. If the sector growth keeps pace with Goldman Sachs and TechCrunch's global forecasts, it stands to generate more than £1 billion in sales in 2018.
REWIND
Delivering immersive experience to the world's largest studios, agencies and brands
REWIND chief executive Sol Rogers believes the UK has the best skill set for developing immersive content and is 6-9 months ahead of the US and potentially further ahead of the rest of Europe in delivering it.
REWIND was launched in 2011 and is a creative digital agency delivering immersive experiences for the world's largest studios, agencies and brands, including HBO, NBC Universal, Sony, Red Bull, Rolls Royce and Jaguar. The company is based just outside London and is able to tap into a deep talent pool due to the presence of many other creative industries in the capital.
Mr Rogers said: “All virtual reality and augmented reality companies have evolved from other skill sets. From film visual effects to game design to advertising, they begin to bleed into virtual reality. You need a core set of people with a skill set to be able to do that."
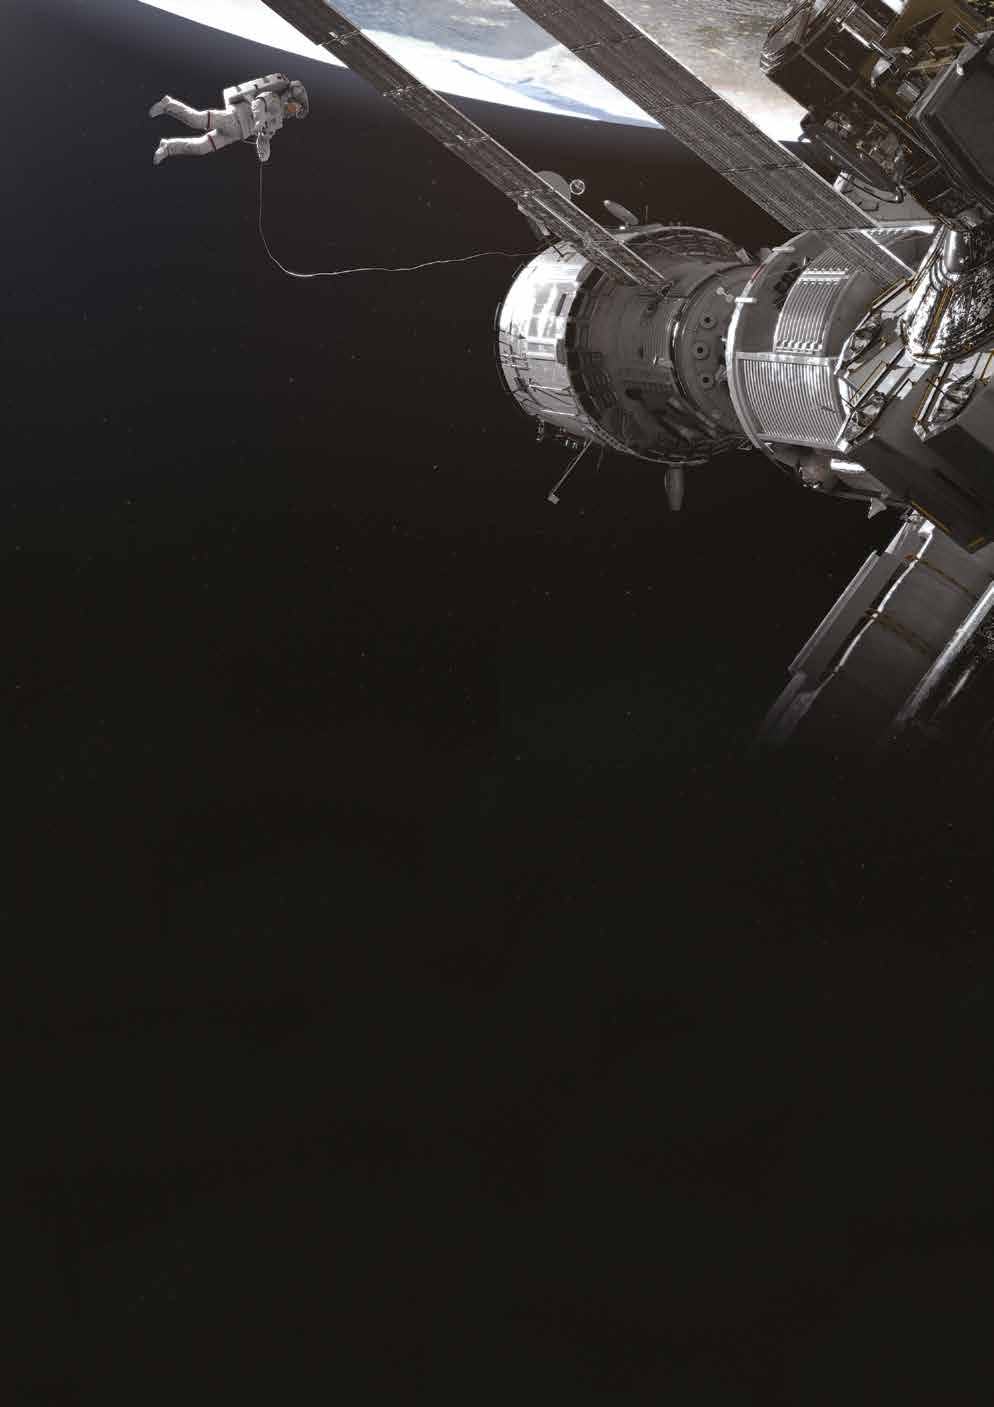
REWIND is associated with market-leading content such as Home, a multiple-award-winning 15-minute immersive virtual reality experience, produced in collaboration with the BBC, that positions the viewer on a space station on a mission to return to base.
Mr Rogers highlighted significant opportunities in the rapid rise of augmented reality and mixed reality in particular. REWIND was one of Microsoft's earliest partners in working on the HoloLens device, and he predicted that augmented reality would be the bedrock for consumer adoption that virtual reality needed.
However, he warned that the industry was expanding quicker than the talent pool available and people were having to be retrained on the job because there were no university courses available.
Sol Rogers
Founder and chief executive
Location
St Albans
Find out more
rewind.co
A young, growing, dynamic and confident sector
Global forecasts based on market research predict explosive growth in the immersive market.
There has been an entrepreneurial boom among immersive specialists. The average specialist company in our data is 6 years old, 3 times younger than the average immersive participant. Half the specialist companies were incorporated after 2012 (see figure below).
The majority of immersive companies we surveyed reported an increase in turnover in the last 12 months. Almost two-thirds of specialist companies grew their sales in the last 12 months compared with just over half of participating companies (see the top bar chart in figure 2).
Figure 1: Number of specialist and participating immersive companies incorporated by year
A bar chart showing the number of companies incorporated by year, broken down by company type (specialist vs. participant). The chart shows a significant increase in both specialist and participant companies from around 1990, with a steep rise after 2000, particularly for specialist companies which peaked around 2010.
Company type legend:
* specialist
* participant
Source: Glass/Nesta analysis (2018)
Figure 2: Changes in turnover and confidence levels in specialist and participant immersive companies
Two bar charts comparing turnover change and confidence levels.
The top chart, "Turnover change in last 12 months (% of companies in category)", shows that a higher percentage of both specialist and participant companies reported "Higher than 12 months ago" turnover compared to "The same as" or "Lower than". Specialists showed a higher percentage for "Higher than 12 months ago" than participants.
The bottom chart, "Confidence for the next 12 months (% of companies in category)", indicates that a very high percentage of both specialist and participant companies are "Very confident" or "Quite confident" about the next 12 months, with "Very confident" being the largest category for both.
Turnover change legend:
* Higher than 12 months ago
* The same as 12 months ago
* Lower than 12 months ago
Confidence legend:
* Very confident
* Quite confident
* Neutral
* Not very confident
We compared our immersive growth data with information about business growth collected for Creative Nation, an analysis over 3 years of the geography of the UK creative industries. This suggested that the proportion of immersive companies growing is bigger than we see generally in the creative industries and in other sectors. This is consistent with markets for immersive products, services and technologies being more dynamic than other parts of the economy, including high-performing creative sectors.
Immersive companies were very confident about the future. Almost 9 in 10 of immersive specialist and participant companies in our survey were 'very confident' or 'quite confident' (around half in each category were 'very confident', see the bottom bar chart in figure 2).
This optimism is also evident in interviews with immersive companies such as Wave Optics (see case study).
WaveOptics
Creating technologies that provide the foundation for augmented reality
WaveOptics is a pioneering, highly specialist producer of waveguides, an essential component of the augmented reality supply chain. The business enables the projection of an augmented image into the eye, blending it into the real world.
Clients of the Oxfordshire-based company include some of the world's largest technology manufacturers, which are integrating WaveOptics technology into their headsets and wearable devices.
Much of the current focus of augmented reality adoption and investment is on military and industrial solutions. But chief executive David Hayes said mass consumer adoption of truly scalable and immersive augmented reality experiences was imminent. He foresaw a shift towards the prosumer (including professionals who can use augmented reality to help them do their jobs) in 2019/2020, and then ultimately the consumer.
Mr Hayes said Apple and Google had already enabled their own platforms for augmented reality, but to generate consumer demand there would need to be "killer apps”.
He added: "Until there's a content repository there's not going to be a consumer market." While things would not change overnight, there would be a huge market, with many tens of millions of headsets coming to the market over the next few years.
Headshot of David Hayes, Chief Executive of WaveOptics.
David Hayes,
Chief executive
Location
Abingdon
Find out more
enhancedworld.com
Immersive is creating value for creative industries and beyond
Our analysis so far has revealed an economically significant, fast-growing sector. But who is buying all this immersive technology? And how does it create value for its users?
A range of sectors
Although immersive mass market products such as consumer headsets are perhaps most visible, business-to-business applications of immersive are also significant. We asked survey respondents what sectors they operated in.
Just over 80% of specialist businesses who responded identified at least one creative/digital sector (including software, advertising, media or games) amongst their markets (figure 3 below shows the percentage of immersive specialist respondents serving each of the markets we asked about in the survey).
Almost two-thirds also identified other 'non-creative' sectors. Training, education, health and tourism are mentioned most often. A small poll of large organisations in Immerse UK's network highlighted significant revenues and expenditures on immersive. This included large automotive businesses spending millions of pounds on immersive technology research and development in recent years, and companies working in construction and manufacturing already generating millions in turnover from these technologies.
Examples of such sector-spanning applications abound among our interviewees (see AMRC, Oxford Medical Simulation and Soluis case studies).
Figure 3: Percentage of specialist immersive companies working in different markets
A horizontal bar chart showing the percentage of specialist companies operating in various markets. Markets are listed vertically, from Media (highest percentage) to Finance (lowest).
The top categories include: Media, Training, Software development, Education, Games, Advertising, Health, Tourism, Architecture, Engineering, Hardware, Manufacturing, Retail, Journalism charities, Defence, Automotive, Data, Other, Telecommunications, Energy, Electronics, Finance.
Percentages range from just over 0% to almost 60%.
Source: MTM Survey/Nesta analysis (2018)
AMRC
Discovering applications of immersive in manufacturing
ADVANCED MANUFACTURING RESEARCH CENTRE
The University of Sheffield.
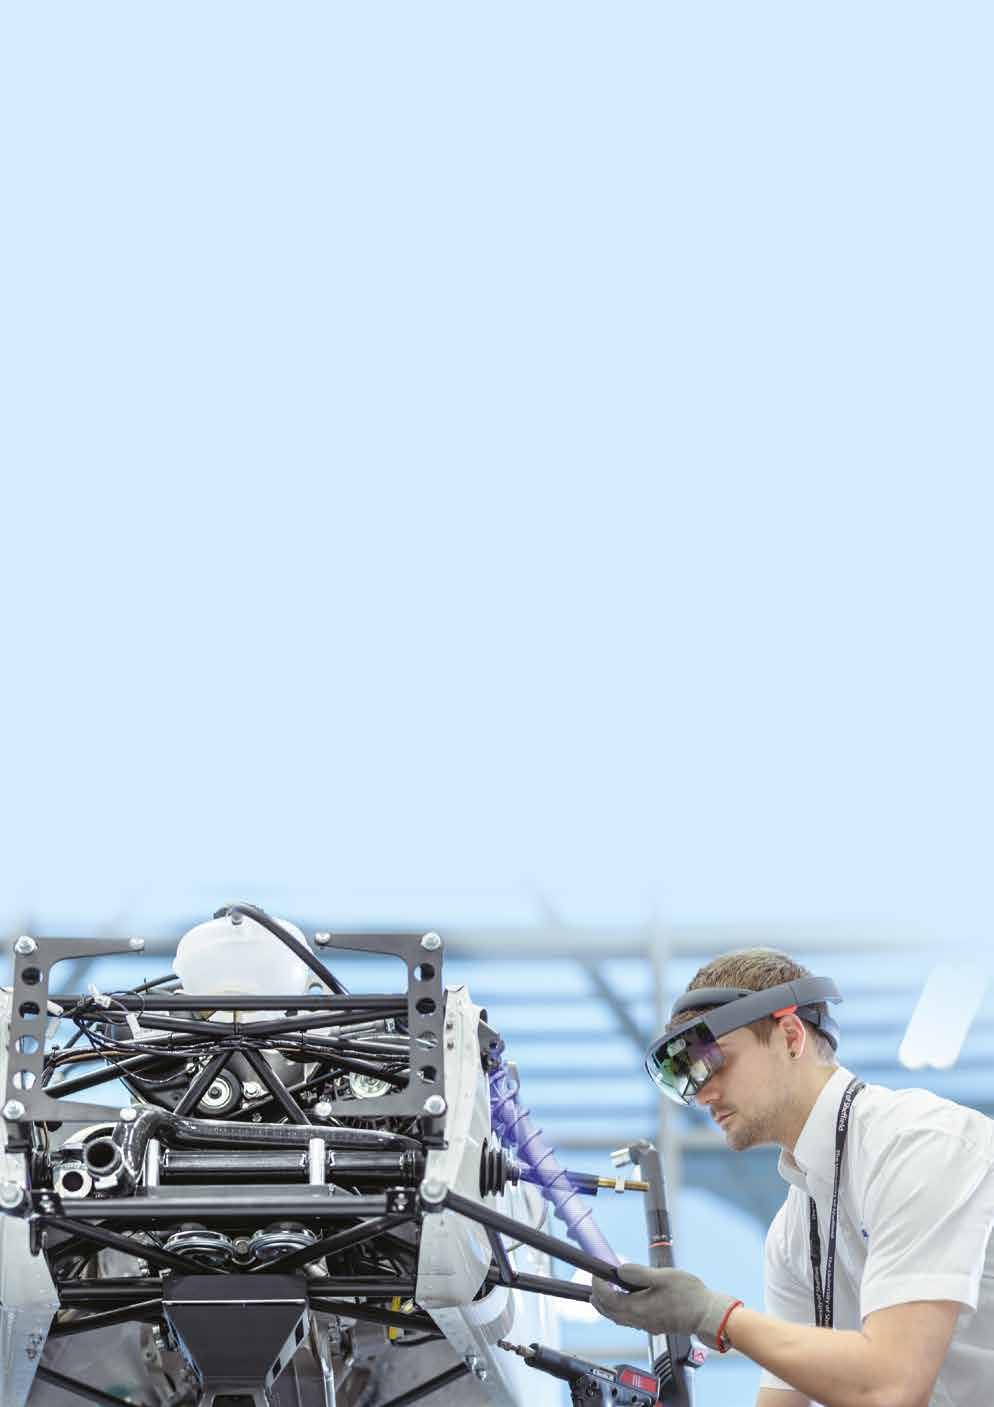
Christopher Freeman, of the Advanced Manufacturing Research Centre at the University of Sheffield, said they had been working with virtual reality since 2003.
"It's quite a well-established technology, the manufacturing industry had been using it for a long time. There's a lot of empirical evidence that shows the benefits and where it could be used.
"New headsets have reduced a number of adoption barriers, in particular ones associated with cost.
"As a result, we can now use that empirical evidence to explore different methods for delivering advanced training and human machine visualisation. Now the tech is more freely available, the focus is on integration, how do we get it linked to a product lifecycle system, how do you get it integrated into an engineering, and factory-live system?"
AMRC, as a not-for-profit research and development centre, works with a wide range of companies across multiple sectors, helping them use new technologies such as virtual reality to improve their businesses.
Mr Freeman added: "We're doing a large project with Yorkshire Water, where we've been proving out the use of virtual reality for a number of engineering processes, showing what's possible. The applications being developed with Yorkshire Water are set to have a transformational impact on how they design and engineer their assets and deliver huge savings."
Christopher Freeman,
Theme lead for digital manufacturing/augmented reality technical fellow
Location
Sheffield
Find out more
amrc.co.uk
Mr Freeman said he saw an advantage in being part of a growing community of immersive technology companies in the region.
He said they were now in the same place with mixed reality and augmented reality that they were with virtual reality 10 years ago.
"A lot of the work in mixed reality and augmented reality is looking at developing the use cases and understanding the system and user experience challenges of the technology. By investing in core R&D now, when the hardware does become available at consumer level, we'll be in a better position to accelerate the time to adoption."
Respondents to the survey participated, on average, in 4 markets, supporting the idea that the opportunities to apply immersive technology stretch far and wide, and that immersive companies are ambitiously exploring those opportunities. For example, Belfast-based VR specialist RETìníZE has a background in high-end film and television production, having begun life in 2014 a subsidiary of the successful production house, Wild Rover. In the last couple of years, however, the client base for the company's virtual reality content has expanded to include NGOs, tourist organisations and global industries.
Sources of value
We identified 4 key sources of value in immersive technologies for respondents:
- product: the ability to develop new and more attractive products, including through faster prototyping, and to increase the visibility of the company as an innovator
- market: the ability to expand the markets the company targets and work with a wider set of collaborators
- process: improvements in organisation and efficiency
- culture: changing the culture of the organisation
Figure 4 presents their responses, showing that the main way immersive technologies create value for our respondents is by enabling them to develop new and better products. More than 8 in 10 flagged this up as an advantage (this includes specialists, participants and 'allied' companies who responded to the survey but did not generate any revenue directly from products based on immersive technology). This is followed by process improvement (which is specially important for participant companies, almost 60% flagged this up as a source of value), market and culture (these 2 types of value are particularly important for allied companies who are using immersive to stand out and develop a culture of innovation). 60% of respondents said that immersive created more than one type of value for them, illustrating the broad scope of potential benefits.
Our interviews suggest that the value of immersive for a business has to be discovered through experimentation and integration (see AMRC, Corporation Pop and Jaguar Land Rover case studies).
Figure 4: Percentage of companies reporting benefits from immersive technologies
A bar chart showing the percentage of companies reporting benefits from immersive technologies across different "Types of benefit": product, process, market, culture, and other. The data is broken down by "Company type": allied, participant, and specialist.
For "product", all three company types show a high percentage, with specialists slightly higher.
For "process", participant companies show the highest percentage.
For "market", allied companies are slightly higher, followed by participant and specialist.
For "culture", allied companies again show the highest percentage.
"Other" benefits are very low across all company types.
Company type legend:
* allied
* participant
* specialist
Source: MTM Survey/Nesta analysis (2018)
Corporation Pop
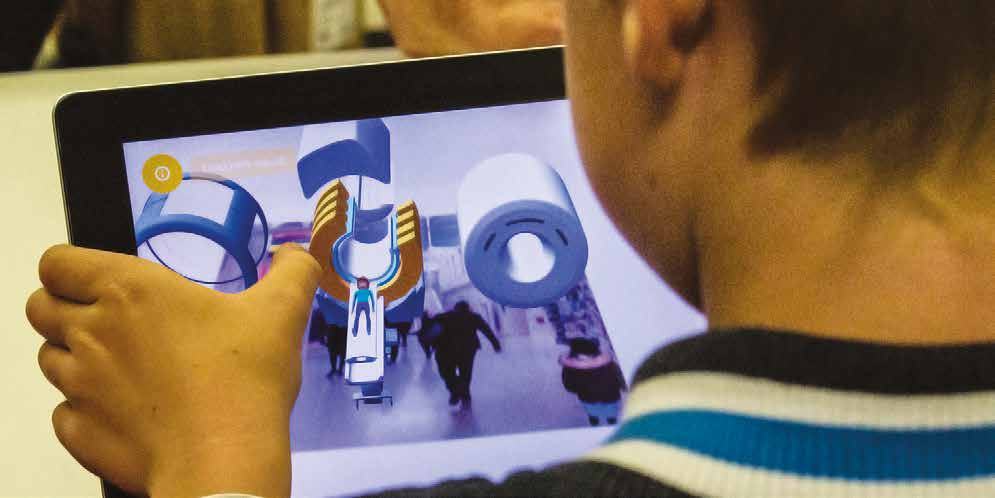
Entering a hospital for treatment is a daunting experience for many young patients. Manchester-based agency Corporation Pop has created a mobile-phone app that allows children to better understand and navigate the medical care they will receive. Using augmented reality, an avatar guides young patients through a series of games and information, making treatment more accessible and enjoyable for children, and their families.
Healthcare professionals, according to Corporation Pop's founder Dom Raban, are increasingly interested in using augmented reality as part of a wider brief to use new technology that will help them interact with their customer in a new way.
He added: "Businesses are finding augmented reality much more tangible for business benefits. Most end-users will have a device capable of displaying augmented reality in one shape or form. Beyond the marketing piece for an exhibition or a trade show, we're getting much more interest in augmented reality."
Mr Raban said there were specific advantages for an immersive company to be based in Manchester.
He added: "There is a real sense of lots of things going on, there's a quite good skill-space up here, which makes a difference. There are several universities running courses that deliver graduates with the skills we need. There is definitely a community of people here."
Headshot of Dom Raban, Managing Director of Corporation Pop.
Dom Raban,
Managing director
Location
Manchester
Find out more
corporationpop.co.uk
Immersive technology is a high-export business
We asked immersive companies about their propensity to export. 70% of the specialist respondents reported that they exported immersive products as did 50% of immersive participants (this compares favourably with the 45% of export-intensive SMEs in sectors such as manufacturing or information and communications identified in the 2016 Small Business Survey) [6].
This supports the idea that UK immersive businesses are internationally competitive and that immersive technologies help companies to export by differentiating their products and services. The global ambition of UK immersive businesses is exemplified by Oxford Medical Simulation, who launched in January at an industry conference in Los Angeles (see case study).
We found that the US was more important for immersive specialists (35% identified it as their major market) while the EU was more important for immersive participants (32% identified it as their major market). See figure 5 for a breakdown of exports.
Figure 5: Export markets for immersive companies
A bar chart showing the percentage of specialist and participant companies that report a given market as their biggest for immersive-related products and services.
For "specialist" companies, "USA" is the dominant biggest market, followed by "Europe" and "Multiple markets are equal".
For "participant" companies, "Europe" and "Multiple markets are equal" are more significant, followed by "USA".
Other markets listed include China, Rest of the World, Middle East, South East Asia, and Japan, with generally lower percentages across both company types.
Export markets legend:
* Multiple markets are equal
* USA
* Europe
* China
* Rest of the World
* Middle East
* South East Asia
* Japan
Source: MTM Survey/Nesta analysis (2018)
Immersive companies are based across the UK
Previous analyses of clustering in Tech Nation, Creative Nation and the Open Data Institute innovation maps have shown that, although much of the innovation activity concentrates in London and the South East, there are other budding clusters elsewhere in the UK [7].
The picture is similar for immersive technologies. Although 38% of the companies in our data are in London, and a further 13% in the South East, we have found hotspots of activity with more than 10 immersive companies in all regions and nations of the UK. This goes from Manchester and Liverpool in the North West to Brighton, Guildford and Oxford in the South East, Newcastle in the North East, Bristol in the South West, Edinburgh, Glasgow and Aberdeen in Scotland, Cardiff in Wales and Belfast in Northern Ireland (see top panel in figure 6 for the top 20 locations in terms of total activity, and the maps in the first row in figure 7, where more intense colours represent locations with higher levels of immersive activity).
When we control for the size of local economies, we identify 14 locations in the UK that are relatively specialised in immersive (these are places where immersive companies are over-represented compared to the UK average). The middle panel in figure 6 and the maps in the second row in figure 7 show which they are. We see, for example, that in Brighton the share of immersive companies is 4 times bigger than the UK average.
We also analysed the sectors where immersive companies operated in each of these locations. The bottom panel in figure 6 shows the percentage of local immersive companies in different sectors based on Glass's classification. The results reflect the wider specialisations of local economies. For example, Oxford, Cambridge and Bristol have significant presence of immersive companies in health and science, while strong creative clusters such as Brighton, Bristol and Manchester are relatively specialised in media. Newcastle has relatively more activity in real estate and construction. All this supports the idea that immersive technology is being developed in ways that respond to the strengths and needs of local economies, with potential benefits for their productivity and competitiveness.
OMS
OXFORD MEDICAL SIMULATION
Medical training simulation goes global
Simulation has become a vital tool for training medical professionals. Traditionally, doctors were taught at medical school and then sent out to wards. But with rising patient numbers and greater visibility of errors, medical simulation has grown in recent years to provide a safer and repeatable way of training medical professionals. Specialised facilities, trained actors and high-fidelity mannequins are combined to create realistic scenarios that test the nurses' and doctors' knowledge, skills and judgement.
"Physical simulation is a fantastic way of learning, but incredibly expensive," said Dr Jack Pottle, a London-based physician and co-founder of Oxford Medical Simulation.
His company's solution is to use virtual reality to create those scenarios. This virtual version offers immersive, interactive emergency scenarios, but crucially less expensively than physical simulation while still allowing students to focus on acute decision-making under pressure.
The company launched in January 2018 at an industry conference in Los Angeles.
Dr Pottle said: "Although we've developed it in the UK, this is a global market. Our first markets are the UK and US, where there's huge appetite for medical training, and using virtual reality makes delivery of it entirely scalable."
For now, the company is focused on pure virtual reality, using Oculus Rift headsets, but the underlying technology is device-agnostic and, as adjacent technologies evolve, Dr Pottle is keen to integrate them, where relevant, into his company's products.
He added: "There will be a shift in voice recognition quality, allowing real-time communication skills training. The use of hand representation and haptics can add to fidelity. There are a huge number of tech angles we could go down but the key at this stage is for the system to be as usable as possible in order to scale."
Dr Jack Pottle
Co-founder
Location
London
Find out more
oxfordmedicalsimulation.com
Figure 6: Immersive hotspots in the UK: levels, specialisation and sectoral composition
This page presents three visual charts:
-
Top Bar Chart (Number of companies): Shows the total number of specialist and participant immersive companies across various UK locations (London, Manchester, Brighton, etc.). London has the highest number of companies, followed by Manchester and Brighton, with numbers decreasing for other locations.
- Company type legend: specialist, participant
-
Middle Bar Chart (Relative specialisation): Illustrates the relative specialisation of immersive companies in different UK locations. Brighton shows the highest specialisation, indicating a high concentration of immersive companies compared to the UK average. Other locations like Bristol, Manchester, and Oxford also show higher specialisation.
-
Bottom Stacked Bar Chart (% of all specialist/participant firms by sector): This chart breaks down the sectoral composition of immersive companies in different UK locations. Each bar represents a location, and the stacked segments show the percentage of companies in various sectors (e.g., Technology, Professional services, Media and arts, Non profit and education, Real estate and construction, Leisure and hospitality, Industrial and agriculture, Consumer goods and services, Healthcare and scientific, Other). This shows varying specialisations across locations, for example, London has a significant portion in Technology and Professional Services, while Brighton shows a higher proportion in Media and Arts.
- Sector legend: Technology, Professional services, Media and arts, Non profit and education, Real estate and construction, Leisure and hospitality, Industrial and agriculture, Consumer goods and services, Healthcare and scientific, Other
Source: Glass/Nesta analysis (2018) and ONS (2017).
Figure 7: Levels of and specialisations in immersive activity across the UK
. Augmented and virtual reality: The promise and peril of immersive technologies https://www.mckinsey.com/industries/media-and-entertainment/our-insights/augmented-and-virtual-reality-the-promise-and-peril-of-immersive-technologies and https://beta.techcrunch.com/2017/01/11/the-reality-of-vrar-growth/
- MarketsMedia (2017). AR Becomes a Reality in Trading https://marketsmedia.com/ar-reality-trading/
- Bresnahan, T. F., & Trajtenberg, M. (1995). General purpose technologies 'Engines of growth'?. Journal of econometrics [65(1), 83-108]
- Bakhshi, H. and Mateos-Garcia, J. (2016). New Data for Innovation Policy http://www.oecd.org/sti/106%20-%20Bakhshi%20and%20Mateos-Garcia%202016%20-%20New%20Data%20for%20Innovation%20Policy.pdf
- Glass https://glass.ai/
- Department for Business, Energy & Industrial Strategy (2016). Longitudinal Small Business Survey Year 2 (2016). https://www.gov.uk/government/uploads/system/uploads/attachment_data/file/624580/small-business-survey-2016-sme-employers.pdf
- Open Data Institute Leeds. UK Tech Innovation Index. http://odileeds.org/projects/uk-tech-innovation-index/?options=true&datagroup=All%20Technology&location=null
- Gustafsson, R., & Autio, E. (2011). A failure trichotomy in knowledge exploration and exploitation. Research Policy [40(6), 819-831]
Technical annex
Machine learning analysis
We have trained a model to predict relevant survey responses (employment, turnover and level of engagement in the immersive economy) based on data that were also available for companies that did not respond to the survey.
These data were obtained from Glass and Companies House. The Glass data included web metrics (size of the website, number of inwards and outwards links, number of personal profiles in the page) and text (we focused on the top 50 words mentioned in the whole corpus, which were particularly useful for predicting which companies are more specialised in immersive). The Companies House data included sector and location.
We trained several models for size, turnover and engagement class labels with 3-fold cross-validation (i.e. testing the robustness of the predictions on a held-out set) and opted for the best performing model (a logistic regression with L1 regularisation). We then used this model to predict the labels in all the companies outside the training set. We ran the model 100 times and allocated each company to the class where it was assigned more frequently.
To produce actual estimates of employment and turnover, we calculated midpoint estimates for each class, based on the distribution of responses in the survey (which relied on a larger number of more finely grained categories than we used in the predictive analysis) and used them to scale each class. Whenever our approach predicted that a company was large in employment, we tried to replace its employment and turnover estimate with actual values from Companies House (this sought to avoid the right censoring of the data caused by the fact that we do not have upper estimates for 'large' employment and turnover categories in the survey).
Our aggregate estimates of employment and turnover for specialist and participating companies are the total predicted employment and turnover for companies predicted to be in that category, averaged over our 100 model runs to increase robustness.
Finding immersive groups in Meetup
In order to find immersive communities in Meetup, we have analysed the keywords through which 3,000 technology meetup groups in the UK describe their activities and interests using topic modelling, a data science method that extracts 'themes' from collections of text. This leads us to identify 43 tech meetup groups in the UK that 'specialise' in immersive (immersive is their 'top topic' according to our algorithms) and 68 groups that do not specialise in immersive but mention it among their interests.
Mining open research data
We created an information retrieval (IR) system for publicly funded research projects that can be queried with words or short phrases and returns relevant items. To do this, we used the text data from research projects funded by research councils, Innovate UK and Horizon 2020.
We assume that when a user queries the search engine, they are interested in a wider set of results including items related to their query. For example, if they are looking for augmented reality projects, we assume they are also interested in virtual reality and mixed reality projects. To implement this, we train word2vec, a text mining model on the project descriptions. Word2vec measures similarities between words based on the context in which they appear. Continuing with our example, "augmented reality" will appear 'close' to "virtual reality" and "mixed reality" in the representation of the text that word2vec creates. We use this to identify the 20 most similar words to our initial query. We then reduce the list's length by removing very common and very rare words.
We then use the resulting list to do a keyword search in the project descriptions and return those projects mentioned in at least one of the queries. In order to rank this list, we assume that the project containing the most queries is the most relevant one and the rest should be sorted based on their similarity with it. To measure this, we train a paragraph vector model (doc2vec) which measures the similarities between documents along the same lines as word2vec does with words. Afterwards, we use KD Tree algorithm to partition the high-dimensional space created by doc2vec. As a result, we receive a list of projects sorted based on their distance with the title of the most relevant project.
Acknowledgements and background
This report was commissioned by Jon Kingsbury at the Knowledge Transfer Network (KTN). Many additional thanks go to Fiona Kilkelly, Carrie Wootten, Tom Campbell, Sol Rogers, Tom Fiddian, Matt Sansam, Sergi Martorell, Joel Klinger, Helen Durham, Anna Zabow, Rich Ellis, Philippe Epailly, Hasan Bakhashi, Darren Murphy, Stephen Greengrass, Rebecca Gregory-Clarke, Aurelien Simon, Jeremy Silver, Chris Freeman, Rab Scott, Shaun Beaney and all contributors to the case studies herein.
Immerse UK, Digital Catapult and the High Value Manufacturing Catapult have been working together on a large-scale programme of business support, funded by Innovate UK, for the UK's immersive technology industries since September 2017. This report forms part of that work along with the following complimentary reports, launching in June and July 2018:
- Growing your VR/AR business in the UK: A business and legal handbook (Digital Catapult & PwC)
- Immersive content formats for future audiences (Digital Catapult & Limina Immersive)
- Evaluating immersive user experience and audience impact (Digital Catapult & Nesta, with i2 Media Research)
- Creative tools and workflows for immersive content creation (Digital Catapult & Opposable Group, with TechSpark)
- Immersive in manufacturing - the adoption and use of immersive technologies in manufacturing and a report covering the feasibility of the use of immersion in a digital twin: High Value Manufacturing Catapult
Innovate UK drives productivity and economic growth by supporting businesses to develop and realise the potential of new ideas.
We connect businesses to the partners, customers and investors that can help them turn ideas into commercially successful products and services and business growth.
We fund business and research collaborations to accelerate innovation and drive business investment into R&D. Our support is available to businesses across all economic sectors, value chains and UK regions.
Innovate UK is part of UK Research and Innovation.
For more information visit innovateuk.ukri.org
Innovate UK
Telephone: 01793 361000
Email: [email protected]
innovateuk.ukri.org
Follow us
LinkedIn
Twitter
Facebook
YouTube
© Innovate UK part of UK Research and Innovation May 2018
18.1137.020